
Inside the defense investing boom fueled by drones, AI and Ukraine
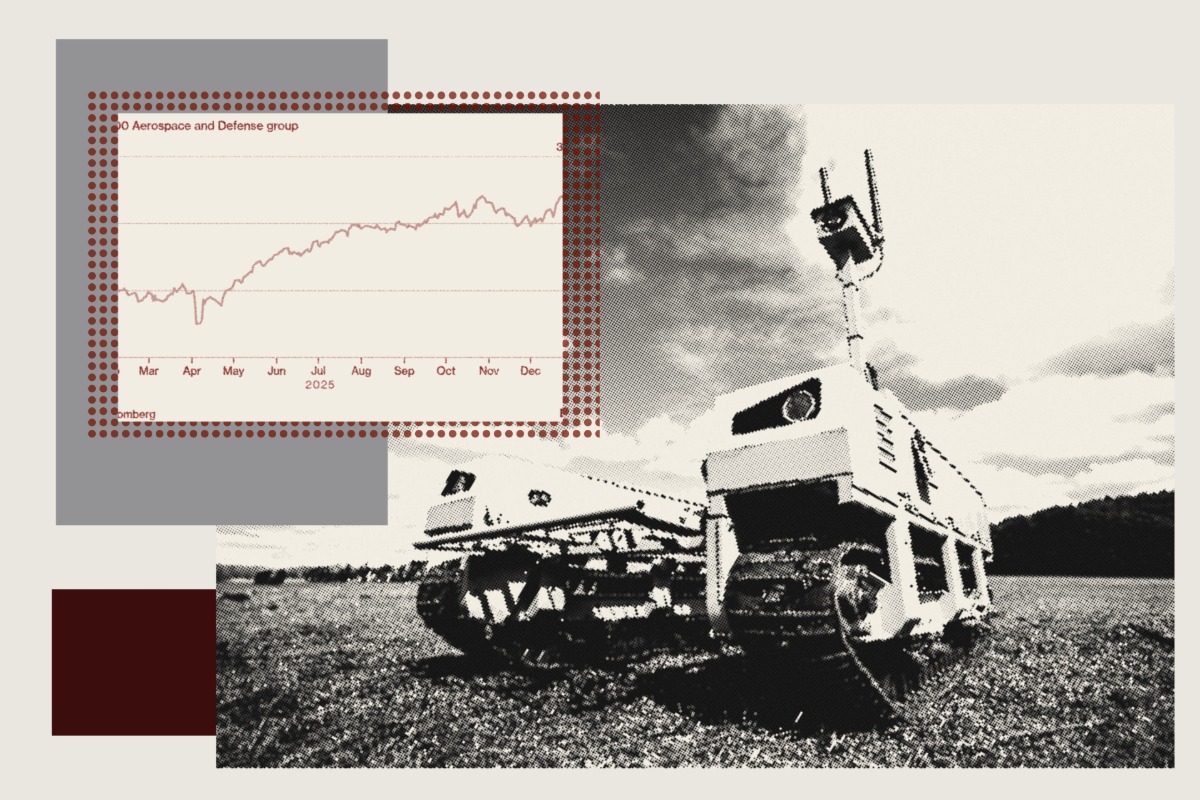
Money is flowing into defense technology at a pace that would have seemed unthinkable a decade ago, and the people writing the checks are not just Pentagon program managers anymore. Individual investors, boutique venture funds and family offices are increasingly betting on drone makers, artificial intelligence startups and companies building weapons for a war in Ukraine that has become, whether intentionally or not, the world’s most closely watched proving ground for next-generation battlefield technology.
To dig into those questions, The Defence Blog spoke with four people who each bring a different vantage point to defense investing: an independent retail investor who researches drones and space technology in his spare time, the CEO of a Swedish venture firm actively funding Ukrainian defense startups, a defense procurement expert who tracks the industry from a U.S. investor’s perspective, and an early investor in Anduril Industries who agreed to share his views only on condition of anonymity, citing the sensitivities of his ongoing business relationships in the sector.
The retail investor, who goes by Chrispy online and describes himself simply as an individual investor and researcher covering drones, space and defense technology in his free time rather than an industry insider, sees the market heading toward consolidation. Asked whether future market leaders will be companies building complete drone systems or those specializing in individual components like autonomy software, sensors and electronic warfare, he pointed to a structural squeeze forming in the middle of the market.
“Rollups and components. There will be waves of consolidation and competitive pressure, execution speed and supply chain management will be the differentiator as far defense premiums move towards commercial numbers and economics (delivery, consumer, etc),” said Chrispy.
A rollup, in industry terms, describes the process of acquiring and merging smaller competitors into a larger combined company, a pattern that has already reshaped industries from waste management to veterinary clinics and appears increasingly likely to sweep through the fragmented drone sector as investors push for scale. Chrispy also offered a framework for evaluating a defense startup before it has locked down major government contracts, pointing new investors toward established business analysis tools rather than hype-driven pitch decks.
“Porters 5 forces analysis, readiness levels (technical, manufacturing, integration, etc) these are great frameworks for LLM assessments, but always validate assumptions before taking them as gospel,” said Chrispy.
Porter’s Five Forces is a business strategy framework, originally developed by Harvard economist Michael Porter, that evaluates a company’s competitive position by examining supplier power, buyer power, the threat of new entrants, substitute products and rivalry among existing competitors, a tool increasingly useful for sorting genuine defense innovators from companies riding investor enthusiasm without a durable competitive moat. On where the strongest long-term opportunity sits within the drone and AI market specifically, Chrispy described a market splitting toward two extremes rather than clustering in the middle.
“I see it as a bit of an inverse bell curve, with ‘neoprime’ players on one side offering diversified ecosystems, and tier II suppliers on the other. Individual drone producers may get squeezed if they fail to differentiate or move to either end,” said Chrispy.
The term neoprime has emerged in defense circles to describe a new generation of venture-backed contractors, companies like Anduril Industries and Palantir Technologies, that aim to compete directly with legacy prime contractors such as Lockheed Martin and Raytheon by building integrated hardware and software ecosystems rather than single products, a structural shift Chrispy’s answer suggests will keep squeezing narrowly focused drone manufacturers caught in between.
Jonas Malmgren, CEO of the Swedish venture firm Front Ventures AB and a Swedish Army Reserve Officer, brought a different lens to the conversation, one shaped by direct experience funding early-stage Ukrainian defense companies through an active war. Asked what motivates investors to take on the financial, regulatory and physical risks of financing Ukrainian defense firms, Malmgren pointed first to the sheer speed at which Ukraine’s homegrown defense industry has matured under combat pressure.
“Main reason is that a new defence industry is being formed in Ukraine across several areas: Drones and drone components, SW for command and control, EW systems, UGV’s etc are all driven from Ukraine and also battle proven and has short and effective ‘development to real usage’ cycles. And valuations so far have been attractive even if the increased in last year. By investing in early stage ukraine companies you get access to proven innovation at a lower comparable cost vs investing in european and US legacy defence companies,” said Malmgren.
Malmgren also pointed to a broader shift underway inside NATO budgets, arguing that traditional heavy armor procurement is already losing ground to drone and electronic warfare investment, citing Estonia’s decision to cancel its planned purchase of CV90 MkIV infantry fighting vehicles as a concrete example of that pivot in action. He described the moral dimension of the calculation as well, acknowledging that some investors accept elevated risk specifically because they want to support Ukraine, and noted that investors are increasingly helping Ukrainian companies establish production sites inside the European Union as a way of securing manufacturing capacity that sits outside an active war zone.
On how investors actually evaluate a Ukrainian company’s technology and growth potential, Malmgren described a deliberate focus on either unique intellectual property or foundational component manufacturing capable of scaling across the industry.
“We either look for unique solutions and IP like Molfar Defence Technologies (C-UAV radar, new design of a radar) or Black Forest Systems (specialized drone for infantry and special forces solidiers) or companies that has knowledge to produce components used by many other companies and can scale fast. Example is Aeromotors who makes full inhouse production of drone motors. Here its also a benefit if the company is not export restricted and can sell outside of Ukraine. Its also for us important there is an initial confirmed need / test agreement in place. So we have focused on supporting companies that has initial LOI’s or test orders and needs to scale up production,” said Malmgren.
An LOI, or letter of intent, is a preliminary agreement signaling that a customer plans to purchase a product once it meets certain conditions, a document investors often treat as an early signal of real demand before a company has secured a binding contract. Malmgren was direct about what he sees as the single biggest obstacle holding back international investment in Ukraine’s defense sector, describing a bureaucratic bottleneck that he argued actively pushes innovation and revenue toward Ukraine’s competitors.
“Easier export approvals. As of August now in 2026 there is only one export approval made for strike drones. No export approvals for interceptors. This limitis sales for ukraine defence companies and makes the investment case lass attractive. Its also a risk ukraine missed the innovation leader benefit of exports are restricted. Then NATO, middle east and Asia is forced to buy from other suppliers at higher cost / less capable systems, but that then fuels innovation outside of Ukraine. So easier export approvals and international joint venture approvals should be prrio 1 for ukraine government,” said Malmgren.
Jeff Gabel, a defense procurement expert, framed the current wave of defense investing partly as a cultural phenomenon layered on top of a genuine strategic shift, cautioning new investors against mistaking public enthusiasm for sound analysis.
“I think investing in defense has become a new way of showcasing support around American sovereignty with a focus on leading the global industry in both manufacturing and might. You see this in swag drops from Palantir and other defense brands, building advocacy around individual investors interested in supporting this space and investing in growth. I think it can be easy to be sucked up into the hype of the investing wave but it’s also critically important to understand the implications around the industry and where legislation is going to back these critical needs. Investors need to pay close attention to earnings call language, geopolitical news, DoW announcements, FAA/FCC regulation and track supply chain cycle to really understand defense investing. While the bucket of defense companies can feel the same in theory, they are not all created equal and require a more in-depth understanding of where each company fits into the value chain,” said Gabel.
On where he sees the strongest opportunity within drones and artificial intelligence specifically, Gabel pointed toward counter-unmanned aircraft systems, technology built to detect and defeat hostile drones, as the space with the clearest dual civilian and military application.
“I believe the biggest threat and most critical dual use opportunity is c-uas as we see it deployed to both the frontline and commercially at home to protect infrastructure (most recently FIFA World Cup) and we need to address future needs to build airspace infrastructure and protect it from those who wish to disrupt it. There’s an important concept around layered defense in that we need to build up a variety of methods in deterrence and there’s no golden bullet that can address all situations. I believe companies are moving to a more complete view of the c-uas landscape, producing products meant for dual use and combining complete needs from software to sensor to system, so agencies can procure off the shelf solutions from one supplier and have complete command and control. The industry as a whole is consolidating to support scaled manufacturing,” said Gabel.
The fourth perspective came from an early investor in Anduril Industries, one of the most closely watched defense technology companies to emerge from Silicon Valley in the past decade, who agreed to speak only if his identity remained withheld, citing the sensitivity of his ongoing business relationships across the sector. Asked what motivates him to fund defense startups in the first place, he argued that chasing this kind of investment purely for financial return misses the point entirely.
“Investing money in defense startups and companies like Anduril or Shield AI just for the money is pointless. This should be done by people who want to change the world, who want to make it safer and better,” he said.
He went on to describe why evaluating early-stage defense startups pursuing genuinely novel technology demands real technical depth, arguing that the ideas most likely to reshape the industry often sound the least credible at first.
“You need to have real technical expertise to judge the prospects of startups proposing revolutionary things, because sometimes they sound like fairy tales or the dreams of nerds from university labs, but those are exactly the people who change the world. They drive revolutions, and the defense sector specifically is the foundation that then moves other industries forward too. So I don’t advise people who don’t understand physics to get into these kinds of ventures, unless they have a few extra million they wouldn’t mind losing,” he said.
He was equally direct about the current enthusiasm surrounding his own biggest success.
“As for Anduril, I put money in at a stage when nobody was even dreaming about this venture, and now I’m watching the hysteria around the company and a bunch of fly-by-night funds promising easy, fast money. Be careful with that. The market for companies like this is usually fairly conservative and doesn’t let newcomers in, and when it does open up, it’s often because of some kind of trouble, and the risk of losing money there is often greater than investing in a small, unknown startup out of Florida or Texas,” he said.
Taken together, these four perspectives point toward a few practical takeaways for anyone actually weighing money on defense technology right now. Watch for consolidation rather than betting on standalone drone makers that lack a clear technical edge or a defined place in the value chain. Treat export policy, not battlefield risk, as the real variable to track when evaluating Ukrainian companies, since a country’s regulatory posture can cap a startup’s growth far more decisively than the war itself.
Look toward dual-use technology, particularly counter-drone systems, where military necessity and civilian demand for protecting infrastructure genuinely overlap rather than merely coexist. And perhaps the hardest advice to follow: the easiest money was made by people who backed unproven ideas before anyone else believed in them, which means the crowded, hyped opportunities getting the most attention today are, almost by definition, no longer where the outsized returns are likely to come from.
Content preview only. Full article available at source. View Full Article
Investment in defense technology, particularly in drones and AI, is surging, driven by the ongoing conflict in Ukraine. Ukrainian defense startups are maturing rapidly, attracting international investors despite bureaucratic challenges. A shift in NATO budgets is noted, favoring drone and electronic warfare over traditional heavy armor. Experts emphasize the importance of dual-use technologies, particularly counter-drone systems, as critical for both military and civilian applications.
- Investment in defense technology is increasing from various sources, including individual investors and venture funds.
- Ukrainian defense startups are rapidly maturing under combat pressure, attracting international investment.
- There is a shift in NATO budgets from traditional heavy armor to drone and electronic warfare investments.
- Export approval bottlenecks are hindering the growth of Ukraine's defense sector.
- Counter-unmanned aircraft systems are identified as a key area for dual-use technology.